Why Start From Scratch? How to Buy an Existing Business in the UK
A practical guide to finding opportunities, checking the evidence, arranging finance and avoiding expensive mistakes
Starting a business is often presented as the ultimate entrepreneurial adventure: find an idea, build a brand and create everything from the ground up.But that is not the only route into business ownership.
Instead of beginning with an empty order book, an unknown name and no established systems, you could buy a business that already has customers, revenue, suppliers and a track record.
For women considering a career change, looking for greater control over their working lives or wanting to turn existing leadership experience into something of their own, buying an established business may be an option worth exploring.It is not necessarily easier than starting a business. It involves different risks, and a poor acquisition can become an expensive problem. However, with careful research, professional advice and realistic financial planning, buying the right business can provide a much stronger starting position.
This guide explains where to look, how the buying process works, what funding may be available and how to investigate a business before committing your money.
Why consider buying an existing business?
- Paying customers
- Recognisable branding
- Trained employees
- Relationships with suppliers
- Equipment and premises
- Websites, systems and processes
- Reviews and a trading reputation
- Evidence of income and expenditure
You are not simply purchasing a name. You may be buying an existing commercial engine.
That can make it easier to assess whether there is genuine demand for the product or service. A startup usually relies heavily on forecasts. An established business should have accounts, sales records and trading evidence that can be examined.
There can also be opportunities to improve a business that is fundamentally sound but has been neglected. An owner may be retiring, relocating or simply ready to do something different. The company might need stronger digital marketing, better systems, new products or a clearer growth strategy.
Those improvements could be areas where your existing experience creates value.However, existing businesses can also carry existing problems. These may include falling sales, outdated equipment, dissatisfied employees, poor contracts, tax liabilities or an owner whose personal relationships generate most of the revenue.
The objective is not simply to buy a business. It is to buy a business whose advantages outweigh its risks—and whose future does not disappear when the seller leaves.
Decide what you are really looking for
Before looking through business-for-sale listings, define your acquisition criteria.
Without clear criteria, it is easy to become distracted by an attractive café, beautiful shop or impressive turnover figure that does not fit your finances, skills or preferred lifestyle.
Consider the following questions:
What experience can you bring?
- Managing people
- Winning or retaining clients
- Budgeting
- Project management
- Marketing
- Operations
- Recruitment
- Compliance
- Technology
- Customer service
- Negotiating contracts
You do not have to buy a business identical to your previous employment. Look for one where your transferable skills could solve important problems.
How involved do you want to be?
Some businesses require the owner to work in them every day. Others have managers and employees handling day-to-day operations.
Be honest about whether you want to:
- Buy yourself a full-time job
- Manage a team
- Oversee the business strategically
- Work remotely
- Build the business before selling it
- Own several small businesses eventually
A company advertised as “owner managed” may rely heavily on the seller working long hours. Ask what would need to be replaced when that person leaves.
What can you afford?
The purchase price is not the only cost.You may also need money for:
- Solicitors
- Accountants
- Surveys
- Valuations
- Lender fees
- Insurance
- Repairs or new equipment
- Working capital
- Marketing
- Staff wages
- Unexpected expenses
A business can appear profitable on paper and still run out of cash. Do not invest every available pound in completing the purchase and leave nothing for running it.
What are your non-negotiables?
These might include:
- Location
- Maximum purchase price
- Minimum annual profit
- Number of employees
- Working hours
- Ability to work from home
- Type of customer
- Regulated or non-regulated sector
- Lease commitments
- Environmental or ethical considerations
Writing these down will make your search much more disciplined.
Where can you find businesses for sale?
There is no single UK marketplace containing every available business. Buyers often need to search several sources.
General UK marketplaces include:
For online businesses, websites and ecommerce companies, you could also examine:
Listings should be treated as advertisements rather than verified statements. Figures supplied by sellers or brokers still need to be checked independently.
Business brokers can introduce buyers to opportunities, including businesses that are not being publicly advertised. The British Business Brokers Association provides information about the sector and a way to identify brokers.
You can also approach owners directly. Accountants, solicitors, industry associations and commercial property agents sometimes know of owners considering retirement or a sale before the business reaches a marketplace.
A direct approach should be respectful. A brief message explaining your interest in the sector may begin a conversation, but do not assume that an owner wishes to sell.
Understand what you are buying
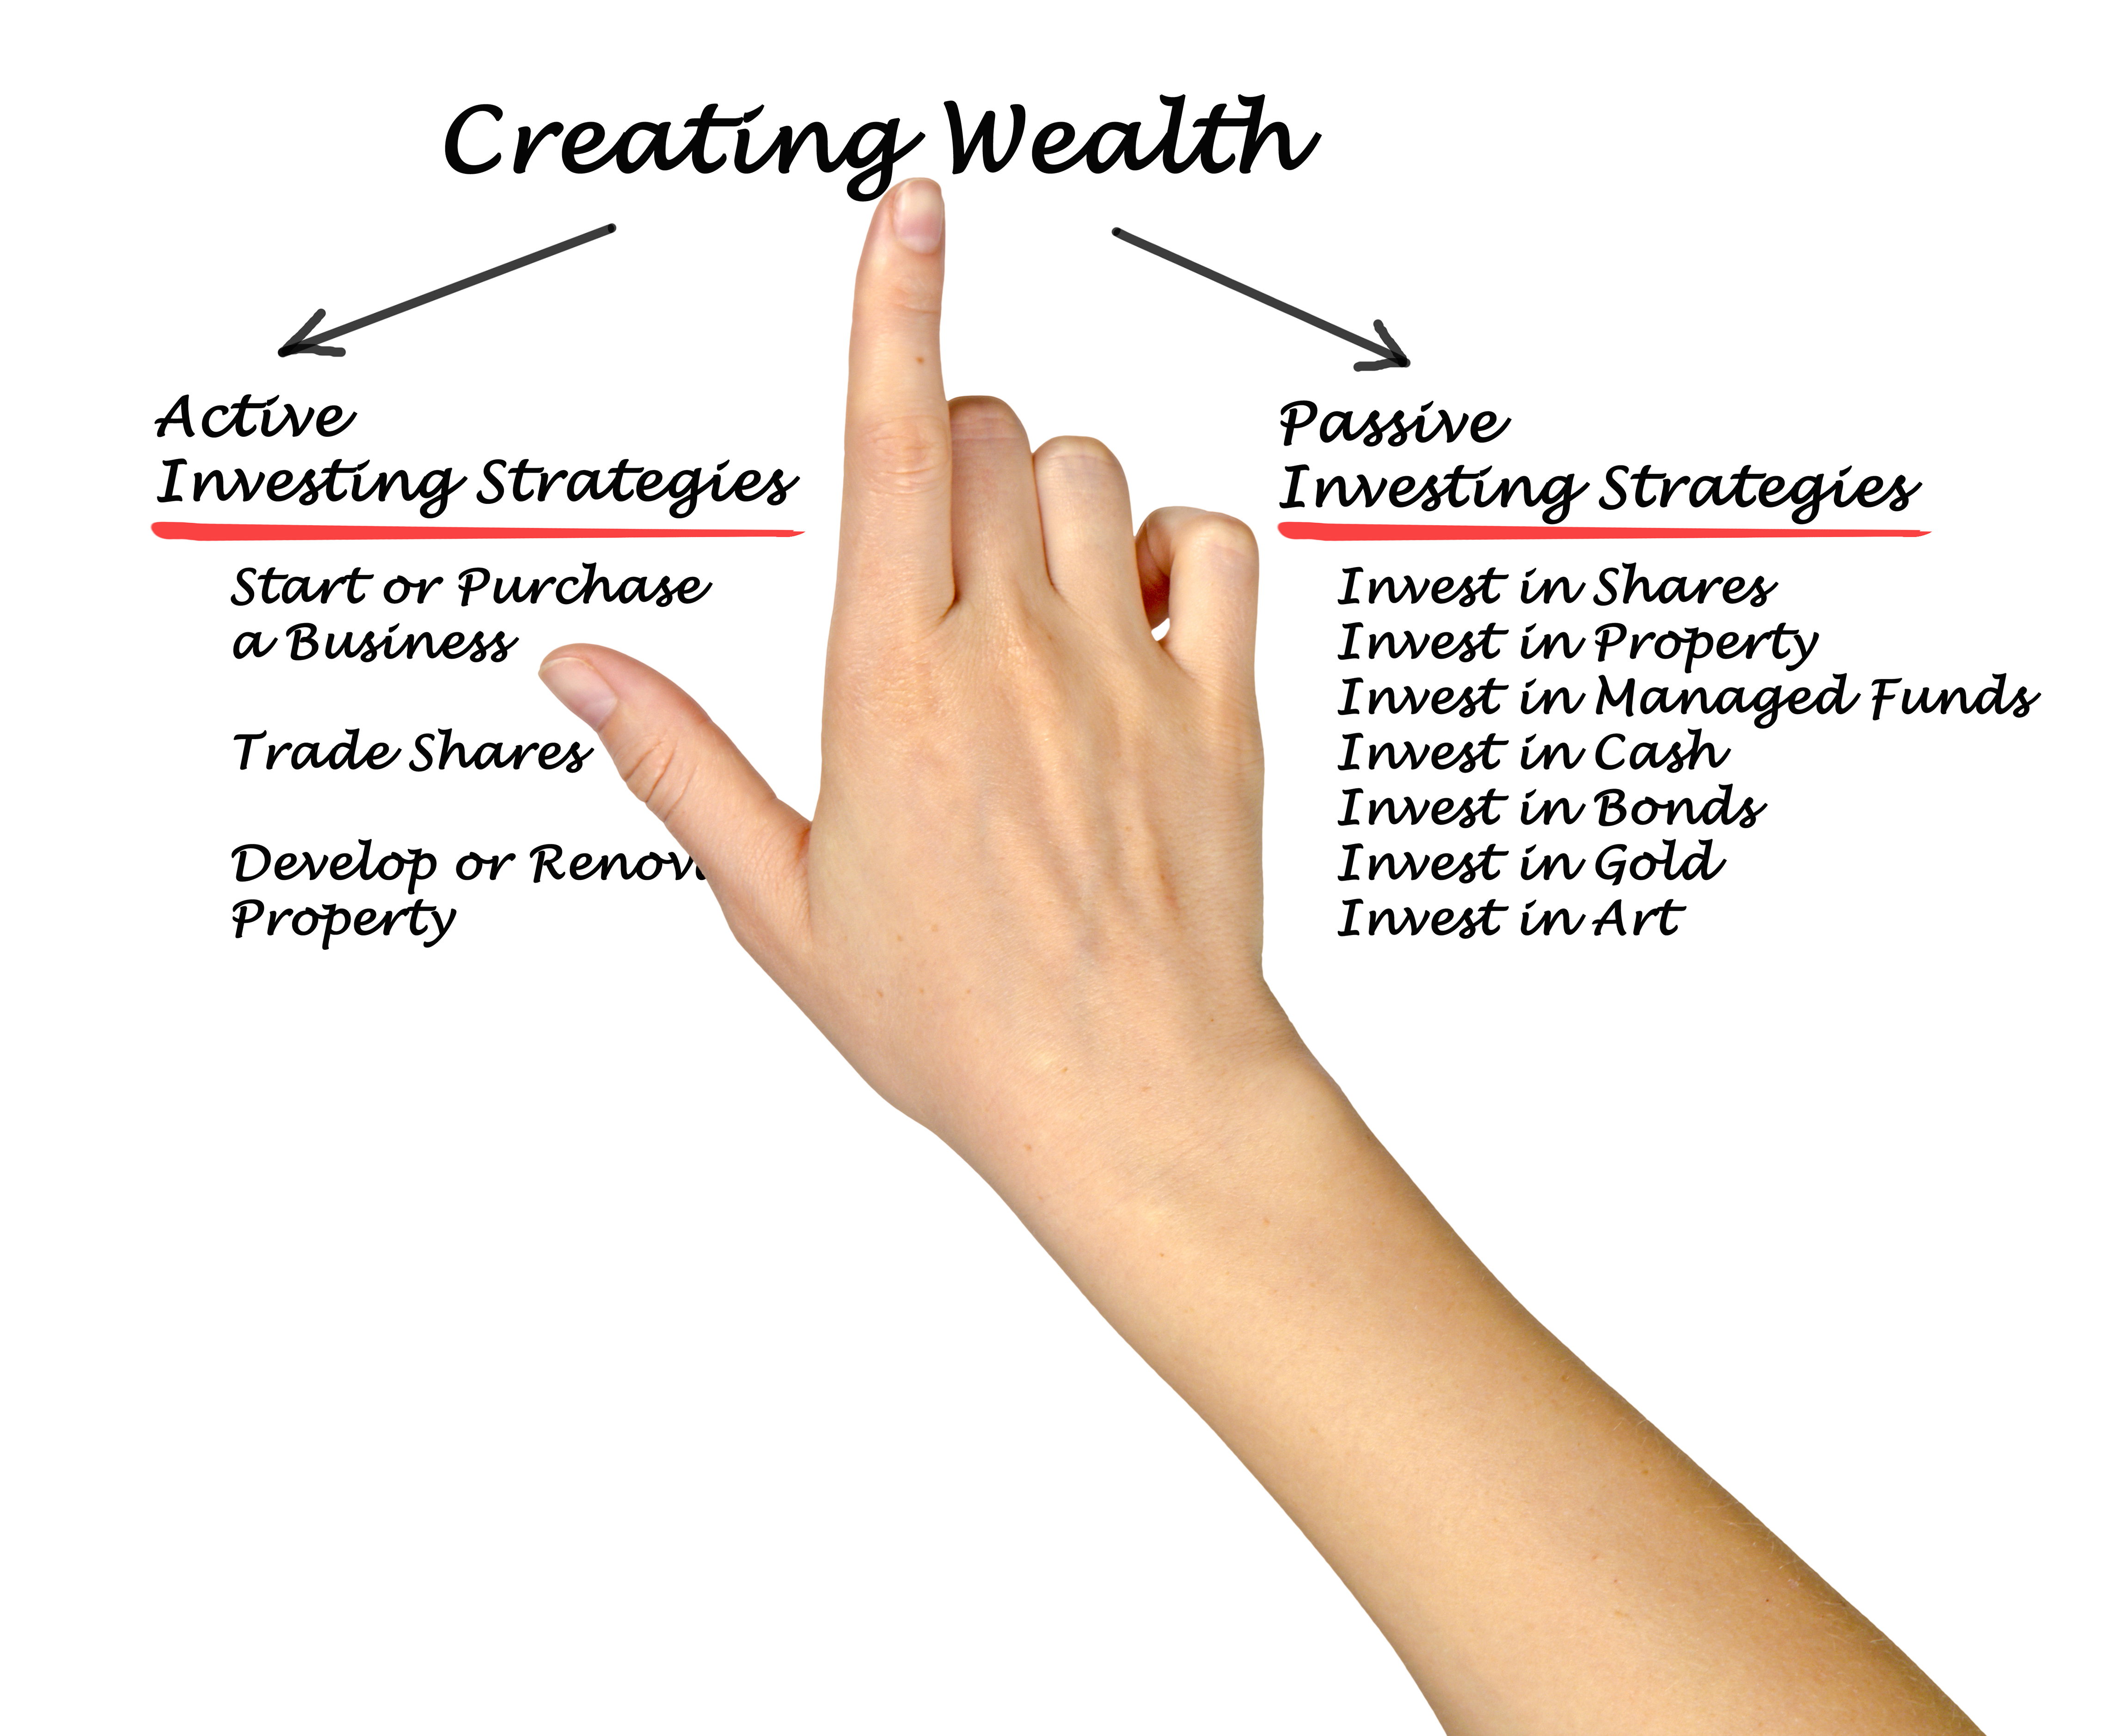
A business purchase will commonly be structured as either an asset purchase or a share purchase.
Asset purchase
You purchase selected assets from the business. These might include:
- Equipment
- Stock
- Customer lists
- Intellectual property
- Websites and domain names
- Contracts
- Goodwill
You can sometimes choose which assets and liabilities are included, subject to negotiation and legal requirements.
Share purchase
You purchase the shares in the company itself. The company continues to own its assets, contracts and liabilities.
This can make continuity easier, but it also means that historic problems may remain inside the company. Thorough legal, financial and tax due diligence becomes particularly important.
Purchasing shares may also attract Stamp Duty, usually calculated at 0.5% of the transaction value, although the exact treatment should be confirmed for the individual deal. Current information is available from GOV.UK.
A solicitor experienced in business acquisitions should advise on the most suitable structure and the protections required in the purchase agreement.
The buying process
Although every acquisition is different, the process usually follows several broad stages.
1. Initial enquiry
You request further information about the business. Before receiving commercially sensitive information, you may be asked to sign a non-disclosure agreement.
2. Review the initial information
You might receive an information memorandum, summary accounts or an explanation of the business model. At this point, you are deciding whether the opportunity deserves more investigation—not whether you are ready to buy it.
3. Meet the owner
Ask why the business is being sold, what the owner does each day and what would happen if they stopped working tomorrow. Pay attention to whether the answers are clear and consistent.
4. Make an indicative offer
An initial offer may be subject to finance, contract and satisfactory due diligence. It may describe the proposed price, payment structure, included assets, transition arrangements and expected timetable.
5. Heads of terms
Heads of terms record the main points agreed in principle. They are not normally a replacement for the final legal documents. They may include a period of exclusivity during which the seller agrees not to negotiate with another buyer.
6. Due diligence
Your advisers examine the company in detail. This is your opportunity to verify what you have been told and identify liabilities or risks.
7. Finance and final negotiation
The results of due diligence may affect the price or structure. You might request warranties, indemnities, a retention of part of the purchase price or changes to the payment terms.
8. Contracts and completion
Once the finance, legal agreement and practical arrangements are in place, the transaction can complete and control of the business transfers.
How might you fund the purchase?
Many buyers use a combination of funding rather than one source.
Personal funds
Using your own savings may simplify the purchase, but concentrating too much of your personal wealth in one business creates risk.
Keep separate provision for emergencies and working capital.
Bank or specialist lending
A lender will normally want to understand:
- The purchase price
- Your contribution
- The business’s financial performance
- Your skills and experience
- How the loan will be repaid
- What security or personal guarantees are available
The British Business Bank Finance Finder can help businesses explore possible finance routes.
Start Up Loans
The government-backed Start Up Loans programme may be relevant in some business acquisitions, provided the applicant and business meet its eligibility rules.
Eligible individuals may apply for up to £25,000, and more than one eligible partner may sometimes apply in connection with the same business. Check the current interest rate and requirements on the Start Up Loans website, as terms can change.
Seller finance
The seller agrees to receive part of the price over time.
This can reduce the amount needed at completion and may indicate that the seller has some confidence in the business’s continued performance. However, repayment terms must remain affordable if trading becomes difficult.
Earn-out
Part of the price is linked to the business achieving specified results after completion.
This can bridge a disagreement about what the company is worth, although earn-outs need precise definitions to prevent later disputes.
Investors or business partners
Another person may contribute money, skills or industry knowledge in return for equity.
Any partnership should be governed by a proper agreement covering decision-making, responsibilities, pay, future investment and what happens if someone wants to leave.
Asset finance
Specific equipment, vehicles or machinery may be financed separately, reducing the amount required for the overall purchase.Be particularly careful with personal guarantees. Government guidance explains that a lender may pursue the guarantor personally if the business cannot meet the debt. Obtain independent advice before signing one.
What does due diligence involve?
Due diligence is not a formality. It is the process of testing whether the business is what the seller says it is.
The British Business Bank’s due-diligence checklist provides a useful starting point.
Areas to investigate include:
Financial information
Request and examine:
- Filed accounts
- Management accounts
- Bank statements
- Tax returns
- VAT records
- Aged debtor and creditor reports
- Payroll records
- Cash-flow forecasts
- Details of loans and finance agreements
- Stock records
- Capital expenditure requirements
Do not rely only on turnover. Examine profit, cash generation and the adjustments used to produce any seller’s estimate of earnings.
Customers
Ask:
- How many active customers are there?
- What percentage of sales comes from the largest customers?
- Are customers under contract?
- Can contracts transfer to a new owner?
- How frequently do customers leave?
- Are relationships with the owner personally?
- Are there outstanding complaints or refunds?
A company with impressive revenue may be fragile if one customer produces half of it.
Employees
Review:
- Employment contracts
- Pay and benefits
- Holiday liabilities
- Pensions
- Disputes and grievances
- Reliance on key employees
- Vacancies
- Contractor arrangements
- Training and licences
Employees may transfer with the business under the Transfer of Undertakings regulations, commonly called TUPE. Obtain appropriate advice and consult ACAS guidance on TUPE.
Legal and regulatory matters
Check:
- Trading licences
- Planning permissions
- Data-protection compliance
- Insurance
- Litigation
- Health and safety
- Industry regulations
- Customer and supplier contracts
- Intellectual property
- Lease terms
- Restrictive covenants
Assets and stock
Confirm:
- Who owns each important asset
- Whether anything is leased or financed
- The age and condition of equipment
- Whether maintenance has been deferred
- How stock is valued
- Whether stock is obsolete or damaged
Online assets
For a digital or ecommerce business, investigate:
- Website traffic sources
- Search rankings
- Advertising accounts
- Email subscriber consent
- Social-media accounts
- Domain ownership
- Conversion rates
- Refund and chargeback rates
- Platform dependence
- Cybersecurity
- Ownership of content, designs and code
Screenshots are not enough. Ask for evidence that can be verified.
Independent checks
You can examine a UK company’s filing history, officers and registered charges through Companies House.
You can also check registered trademarks through the UK Intellectual Property Office search service.
These checks are useful, but they do not replace professional legal and financial investigation.
Warning signs that require more investigation
Be cautious if:
- The seller refuses to provide documents
- Financial figures change without explanation
- Sales have declined sharply
- One customer provides most of the income
- The business depends entirely on the owner
- Important agreements are verbal
- Staff appear unaware of key plans
- Equipment needs immediate replacement
- The lease is close to expiry
- Reviews reveal repeated unresolved complaints
- Website traffic comes from one unstable source
- The business has unusual related-party payments
- The seller is placing pressure on you to complete quickly
- You are told not to speak to professional advisers
One concern does not automatically make a business unsuitable. It does mean that you need an adequate explanation and, where appropriate, contractual protection or a revised price.
Real acquisition stories and the lessons behind them
The Tofoo Co: buying something small and building the brand
In 2015, Dave Knibbs and Lydia Smith bought a small tofu producer in Yorkshire and developed it into The Tofoo Co.
Rather than starting a food-manufacturing business from nothing, they acquired an existing product and production base, then changed the branding, packaging and commercial approach.
The company subsequently grew into a nationally recognised tofu brand. The founders sold a majority stake in 2024 in a deal reported to value the company at more than £35 million, while retaining a minority interest and continuing as directors.
The lesson is not that every small acquisition will become a multimillion-pound company. It is that an overlooked business can sometimes provide a foundation for a much bigger idea.
The value may lie in what already exists combined with what a new owner is capable of adding.
Three women who chose acquisition
An Acquiring Minds panel brought together three women who had entered business ownership through acquisition.
Cassi Niekamp acquired Bowden Fence, a long-established fencing company. The financing and valuation process nearly prevented the deal from completing, showing that obtaining lender approval is not always straightforward even when the underlying business is established.
She also had to enter an industry in which she had no previous technical background and earn the confidence of employees and customers.
Morli Desai acquired the ecommerce business Amaira Natural Skincare in 2022. Her experience highlights the attraction of buying a company that can be operated flexibly, but also the need to understand digital marketing, customer acquisition and the realities behind online-business figures.
Anne Ristic moved into entrepreneurship after a 35-year legal career, acquiring Agency Employment Services at the age of 60.
Her story is a valuable reminder that acquisition is not reserved for people at the beginning of their careers. Decades of professional experience can become an advantage when evaluating risk, managing people and leading an established organisation.
A recurring message from these experiences is that buyers do not need to possess every skill personally. They do, however, need to recognise their gaps, listen to the people already inside the business and build the right professional and operational support.
A cautionary coffee-business account
Success stories are useful, but difficult experiences can be equally instructive.In a public Reddit account of buying a coffee business through seller finance, the buyer wrote:
“I underestimated how fast cash flow can kill you.”
The buyer described inheriting equipment problems, staffing pressures and insufficient working capital while still needing to make payments to the seller.
This is one person’s account rather than independently verified research, but the underlying warning is important: agreeing a purchase price is not the same as proving that the business will have enough cash to survive.
Before completion, model what would happen if sales fell, an important employee left, equipment failed or customers paid late.
Questions to ask the seller
When you meet the owner, consider asking:
Why are you selling?
What do you personally do every week?
Which relationships depend on you?
What are the business’s three biggest risks?
Which customers generate the most revenue?
Which employees are essential?
What investment will be needed during the next two years?
Have sales or margins declined?
Are there disputes, complaints or legal issues?
What would you change if you kept the company?
Will you provide training and a handover?
Would you accept part of the price over time?
Are you willing to agree not to establish a competing business?
What information can be supplied to verify your answers?
The seller’s manner is not proof, but reluctance, inconsistency or excessive pressure should affect how you proceed.
A practical 30-day starting plan
You do not need to begin by making offers. Start by learning how opportunities are described and valued.
Week one: define your criteria
Write down:
- Your available investment
- Preferred industries
- Location
- Working hours
- Existing skills
- Income requirements
- Maximum level of risk
- Activities you do not want to perform
Week two: study the market
Review at least 20 listings.
Record:
- Asking price
- Turnover
- Claimed profit
- Number of employees
- Reason for sale
- Location
- Assets included
- Points requiring clarification
This will help you recognise exaggerated claims and understand the language used by sellers and brokers.
Week three: build your advisory circle
Identify:
- A solicitor experienced in business acquisitions
- An accountant who undertakes financial due diligence
- Possible lenders or finance advisers
- A business mentor
- Someone with experience in the target industry
Ask about likely fees early so they can be included in your budget.
Week four: make careful enquiries
Select three to five opportunities that meet your criteria.
Request further information, compare the responses and continue only where the evidence deserves more investigation.
Your first objective is not to complete a purchase. It is to become a more capable buyer.
Before you sign anything
Do not allow enthusiasm to replace evidence.
A business can have an appealing story, a friendly owner and an attractive brand while still being a poor investment.
Take enough time to understand:
- What produces the profit
- What consumes the cash
- What will change when the seller leaves
- What could go wrong
- How much money will be needed after completion
- Whether the business suits your capabilities and life
Use qualified legal, financial and tax advisers. Their work adds cost, but the cost of discovering a serious problem after completion can be much greater.
Your next career move could be ownership
You do not have to invent the next revolutionary product to become a business owner.
You may be able to take something that already works, protect what makes it valuable and improve the areas where your experience can make a difference.
The right acquisition could provide income, independence and a platform for growth. The wrong one could create significant financial and personal pressure.
The distinction is rarely luck alone. It is usually found in preparation, realistic numbers, careful due diligence and the willingness to walk away when the evidence does not support the deal.
Start by exploring the market. Learn how businesses are valued. Build your advisory team. Then decide whether buying an existing business could be the next chapter in your working life.
This article provides general information and is not legal, financial, investment or tax advice. Obtain advice appropriate to your individual circumstances before buying or financing a business.